
Buying the share it did not own
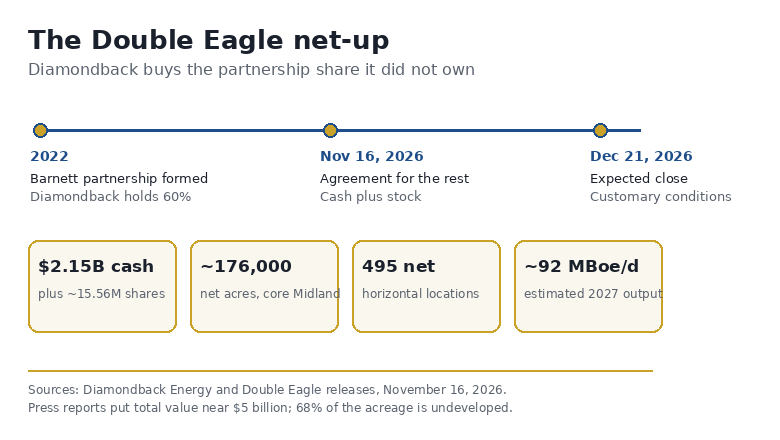
Diamondback Energy announced on Monday, November 16 that it has entered a definitive agreement to acquire certain subsidiaries of Double Eagle IV Midco and Double Eagle V Midco. The consideration is $2.15 billion of cash plus approximately 15.56 million shares of Diamondback common stock, subject to customary adjustments; press reports put the total value near $5 billion. The cash portion is expected to come from cash on hand, borrowings under the company's credit facility, term loans, or a combination. Closing is expected on December 21, 2026, subject to customary conditions. [1,3,4]
Chief executive Kaes Van't Hof described the transaction as a "netting up": Diamondback formed a partnership with the Double Eagle team in 2022 around the emerging Barnett zone in the Midland Basin, and this deal buys the roughly 40 percent of that partnership it did not already own. He said the company does not need to add a rig or materially change its development plan to integrate the assets. [1]
Double Eagle is not exiting the basin. The Fort Worth-based companies, backed by EnCap Investments, Elda River Capital, Apollo Natural Resources and other institutional investors, will keep a multi-rig development program on retained acreage in Reagan County. EnCap partner Kyle Kafka said the firm looks forward to becoming a significant Diamondback shareholder through the stock consideration. [2]
What the money buys
The assets cover approximately 176,000 net acres in the core of the Midland Basin, with estimated 2027 production of about 35,000 barrels of oil per day, or 92,000 barrels of oil equivalent per day at 38 percent oil. Some 68 percent of the asset is undeveloped: Diamondback counts more than 1,200 estimated gross horizontal locations, 495 of them net, in primary development targets with average lateral lengths above 11,500 feet, plus 101 gross drilled-but-uncompleted wells. [1]
The release also disclosed early results from Spanish Trail in Midland County, the partnership's first full-section Barnett development: four wells with 10,000-foot laterals recently peaked at about 7,500 barrels of oil per day and 37 million cubic feet of gas per day, which the company said exceeded its internal expectations. Diamondback plans full-field Barnett development in 2027. Company-reported well results are a snapshot, not a decline-curve forecast. [1]
The math management is selling
Diamondback values the acquisition at about 4.0 times estimated 2027 EBITDA and says it will be immediately accretive to cash flow per share, free cash flow per share and net asset value per share, while remaining leverage neutral. Estimated 2027 EBITDA is a forward-looking, non-GAAP figure defined by the company; the accretion statements are management's, not verified outcomes. [1]
Analysis: the structure tells the story as much as the price. Paying roughly 60 percent stock and funding the rest from existing liquidity lets Diamondback add inventory without adding leverage or rigs. For a public exploration and production company, undeveloped core locations are the scarce input; buying them from a partner whose economics it already knew, in a zone it had been delineating together since 2022, is a lower-information-risk way to extend drilling runway than bidding in an open auction.
The consolidation pattern continues
This is Diamondback's second transformative Permian transaction in under three years, after the $26 billion Endeavor Energy merger announced in February 2024. It is also the latest in a series of public operators buying out private-equity-backed Permian platforms; the company's own filing language notes a separate pending acquisition of Deep Blue. [1,5]
Analysis: for energy costs and investment, the signal is where capital is going. Buyers are paying for undeveloped inventory and subsurface confidence rather than current production, and sellers like EnCap are recycling private capital into public stock. That pattern concentrates the best Permian rock in fewer, larger operators with the balance sheets to develop it on their own schedules. For oilfield services and midstream suppliers, fewer and larger customers generally means longer planning visibility but tougher pricing negotiations; for investors, it means Permian exposure is increasingly an equity-market product rather than a private one.
What to watch before December 21
Analysis: three markers will show whether the deal works as presented. First, closing itself: the December 21 date is subject to customary conditions, and the stock portion means Double Eagle's backers carry Diamondback share-price exposure between signing and close. Second, integration: management's promise is no added rig and no material change to the development plan, so any revision to 2027 capital guidance after closing would test that claim. Third, the Barnett: full-field development in 2027 turns the Spanish Trail early results into a program, and results there will show how much of the acquired inventory performs as delineated. None of these is knowable today, and none is a forecast.
Sources and credits
[3] OilPrice, November 16, 2026: reports the transaction at about $5 billion in total value.
Sources checked November 17, 2026. Educational reporting and labeled analysis, not investment, legal or regulatory advice. Company projections, valuation multiples and well results are attributed to their sources, not verified outcomes or forecasts by Xyzenrgy.
Contact Xyzenrgy to discuss the energy questions facing your business: [email protected].